SBA 504 Loans
Program
Build Your Business. Own Your Property. Invest for the Future.
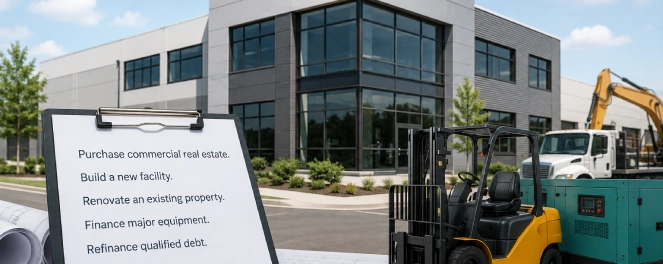
Purchase commercial real estate. Build a new facility. Renovate an existing property. Finance major equipment. Refinance qualified debt.
The SBA 504 Loan Program provides qualified small businesses with long-term, fixed-rate financing for major fixed assets that support business growth and job creation.
At SBACommercialLoans.com, powered by Commercial Lending USA, we help business owners evaluate their projects, structure their financing, and explore SBA 504 and other commercial lending solutions.
Uses of Proceeds
What Can an SBA 504 Loan Finance?
The SBA 504 program is designed primarily for significant long-term business assets rather than short-term operating expenses.
Qualified businesses may use SBA 504 financing for eligible purposes such as:
Purchasing owner-occupied commercial real estate
Acquiring land
Constructing a new business facility
Purchasing an existing building
Expanding an existing facility
Renovating or modernizing commercial property
Improving land, utilities, parking, and landscaping
Long-Term Machinery & Equipment Purchase
Refinancing certain qualified business debt
Financing eligible project-related improvements
Financing eligible project-related improvements
Highlights
SBA 504 Loan Highlights
Structure
How Is an SBA 504 Loan Structured?
Three Parties. One Financing Strategy.
A typical SBA 504 project combines financing from a private-sector lender, a Certified Development Company — or CDC — and the business owner.
A common structure may include:
Private-Sector Lender (Up to 45%): A bank or other participating lender generally provides the senior loan secured by a first lien.
CDC / SBA-Backed Financing (Up to 40%): A Certified Development Company provides the SBA-backed portion, generally secured by a junior lien.
Borrower Contribution (At Least 15%: The borrower typically contributes at least 10% of the total eligible project cost. Certain transactions may require a higher contribution.
This structure can allow qualified businesses to preserve more capital while making a significant investment in real estate or major equipment.
Commercial Real Estate
Buying Commercial Real Estate?
Stop Building Your Landlord's Equity. Start Building Your Own.
For many established businesses, purchasing commercial real estate can be an important long-term investment.
Instead of continuing to lease, SBA 504 financing may help qualified businesses purchase or develop the property they need to operate and grow.
Potential property types may include:
Office Buildings
Medical & Dental Offices
Warehouses
Manufacturing Facilities
Industrial Properties
Hotels & Motels
Restaurants
Automotive Facilities
Daycare Centers
Veterinary Facilities
Assisted Living Facilities
Franchise Locations
Other Owner-Occupied Commercial Properties
Every transaction is different. Property type, occupancy, business performance, project costs, borrower qualifications, and repayment ability can all affect financing.
Comparison
SBA 504 vs. SBA 7(a)
Which SBA Program Is Right for Your Transaction?
Both programs can provide powerful financing solutions, but they are designed for different business needs.
SBA 504 is primarily designed for major fixed assets such as owner-occupied commercial real estate, construction, improvements, and qualifying long-term equipment.
SBA 7(a) offers greater flexibility and may be used for eligible purposes including business acquisitions, working capital, commercial real estate, equipment, and other qualified business needs.
And in some situations, the answer may not be choosing one over the other.
Qualified borrowers may now potentially combine SBA 7(a) and SBA 504 financing for up to $10 million in SBA-backed financing, subject to current SBA rules, eligibility, underwriting, and approval.
Not Sure Which Program Fits?
Send us the transaction. We’ll help you explore the options.
Bank Declines
Has Your Bank Declined the Deal?
One Lender’s Decision Doesn’t Always Define Your Options.
A commercial real estate or equipment transaction may be declined because of a bank’s internal lending policy, industry concentration, property type, project structure, or other underwriting considerations.
At SBACommercialLoans.com, we don’t stop with one financing program.
If SBA 504 isn’t the right solution, Commercial Lending USA can explore other potential commercial financing options.
One Lender Said No? Let Us Take Another Look.
A declined application does not always mean the deal is over. Send us the transaction and let our team review the available financing options.
Submit Your Deal →Partners
SBA 7(a) Loans for Brokers & Loan Officers
Have an SBA Deal You Don't Want to Lose?
Commercial Lending USA works with commercial mortgage brokers, loan officers, business brokers, and referral partners nationwide.
Has been declined by a bank
Has a complicated business acquisition
Needs both business and real estate financing
Requires a creative financing structure
Has an unusual commercial property
Needs an alternative to traditional bank financing
Has a transaction you're unsure where to place
Send Us the Scenario.
Our commercial lending team can review the transaction and explore potential financing options for your client.
Become a Partner
Build more lending opportunities with our team.
Have a Deal?
Send us the scenario and we'll review your opportunity.
Next Step
Ready to Explore SBA 7(a) Financing?
Whether you’re buying a business, purchasing commercial real estate, refinancing eligible business debt, purchasing equipment, expanding your company, or looking for working capital, the right financing structure can make a difference.
Don’t spend weeks approaching lender after lender.
Start With the Transaction.
Let Us Explore the Financing.
Ready to Discuss Your SBA 7(a) Loan?
APPLY ONLINE
Ready to Explore Your Financing Options?
Whether you're purchasing a business, buying commercial real estate, refinancing existing debt, or expanding your operations, our team is here to help you understand your financing options.
Loan Programs
Company
Contact Us
- 855- 90- MYSBA
- sales@sbacommercialloans.com
- 13000 Harbor Dr Suite 228D,
Woodbridge, VA 22192 - Mon - Fri: 10:00 AM - 7:00 PM
SBAcommercialloans.com is operated by Commercial Lending USA. Financing is subject to lender approval, SBA eligibility requirements, underwriting, credit review, and applicable program guidelines. Not all applicants or transactions will qualify. Loan terms, rates, and program availability may vary based on borrower qualifications and lender requirements.
BBB Member
We're A Member Of
© 2026 SBACommercialLoans.com. All rights reserved.